Cash Flow Management Fundamentals for Construction Businesses
Construction companies have always faced challenges when it comes to cash flow. The difficulty largely springs from the often-lengthy gaps between winning projects, doing the work and receiving payments.
As a result, it’s critical for construction business owners and their leadership teams to master the fundamentals of cash flow management. Here are a few to keep in mind.
Banking strategy
Where does your revenue go when you get paid? Hopefully not into a shoebox under your desk! Construction companies need a banking strategy, whereby they consciously plan where to keep their money and in what type of accounts.
Think of your bank as a cash flow management partner. If you’re dissatisfied with the services you’re receiving, you obviously shouldn’t hesitate to shop around. When contacting a prospective bank or working with your current rep, ask about specific ways the institution can help your construction company.
For example, you may be able to create a sweep account that automatically transfers excess funds into an “overnight” investment account. This way, at least some of your funds are earning interest instead of just sitting in checking or savings. Also ask about the latest bonuses and promotions being offered. Banking is a competitive industry these days and you may be able to benefit.
Financial forecasting
Sound financial forecasting is another cash flow fundamental. It involves estimating cash needs by analyzing past billings, tracking payments on current projects, and projecting expected revenue from your backlog, all while keeping a close eye on direct and indirect costs, as well as overhead.
You can prepare forecasts on a job-by-job basis or for the company as a whole. Forecasting’s major benefit is identifying surplus and deficient cash flow periods. Done properly and regularly, it should help you:
- Ensure that cash flow remains at an acceptable level,
- Allocate excess cash for investments or capital goods,
- Set up disbursements to better align with receipts,
- Pinpoint cash deficiency periods to optimize borrowing terms, and
- Identify the clear need for additional working capital.
Precisely how to go about forecasting is beyond the scope of this particular article. Suffice to say that qualified professional advice and the right software can go a long way toward making it a reality.
Report generation and financial statements
Cash inflows for construction companies largely come from accounts receivable. Unfortunately, many contractors struggle with accounts receivable management because they don’t maintain proper documentation or fail to make this documentation available to accounting or financial staff in a timely manner. Subsequently, cash flow suffers.
Choose regular, specific dates to generate accounts receivable reports and ensure those reports are automatically distributed to pertinent employees such as your fellow owners, CFO and project managers. Also, set up monthly meetings to discuss accounts receivable and strategize collections.
Strong financial reporting, including generating financial statements in accordance with Generally Accepted Accounting Principles (GAAP), is another key. After all, along with the income statement and balance sheet, a statement of cash flows is an essential part of GAAP-compliant financial statements. It specifically describes all cash inflows and outflows, whether from operations, investments or financing activities. This is important, insightful data.
Of course, many businesses create a full set of financial statements only once a year. So, be sure to augment your statement of cash flows with more regular cash flow reports. Monthly is common.
Critical function
It cannot be overstated how important cash flow management is for construction companies. We’ve touched on just a few fundamentals in this article. Contact our firm for help with this critical business function.
Benefits of a Construction CPA
The construction industry is a complex and challenging field that requires not only technical expertise but also sound financial management. Whether you’re a contractor, builder, or developer, managing the financial aspects of your construction business can be overwhelming. That’s where a Construction CPA (Certified Public Accountant) comes in. Specializing in the unique financial needs of construction businesses, a Construction CPA can offer a range of benefits that go beyond standard accounting services. In this guide, we’ll explore the key advantages of hiring a Construction CPA and how they can contribute to the success and growth of your business.
Industry-Specific Expertise
The construction industry operates under unique financial and regulatory conditions that differ significantly from other sectors. A Construction CPA, through Cooper Norman, brings specialized knowledge that is tailored to these complexities.
- Why It Matters: General CPAs may not fully understand the intricacies of construction accounting, such as job costing, percentage-of-completion accounting, or the nuances of construction contracts. A Construction CPA, however, is well-versed in these areas and can provide accurate financial guidance specific to your industry.
- Benefit: With a Construction CPA, you gain access to industry-specific expertise that can help you navigate the financial challenges unique to the construction field. This ensures that your financial statements are accurate, compliant, and reflective of your business’s true financial health.
Improved Job Costing and Budgeting
Accurate job costing is essential for profitability in the construction industry. It involves tracking all expenses associated with a project to ensure that costs are within budget and that the project is profitable.
- Why It Matters: Poor job costing can lead to budget overruns, underbidding projects, and reduced profitability. Without accurate costing, it’s difficult to determine whether a project is financially viable or where costs can be controlled.
- Benefit: A Construction CPA can help you implement effective job costing systems that track labor, materials, equipment, and overhead costs accurately. This allows for better budgeting, more accurate project bids, and improved profit margins.
Enhanced Financial Reporting and Compliance
The construction industry is subject to a wide range of financial reporting requirements and regulations. Ensuring compliance while maintaining accurate and timely financial reports is crucial.
- Why It Matters: Non-compliance with financial regulations can result in penalties, legal issues, and damage to your business’s reputation. Moreover, inaccurate financial reporting can lead to poor decision-making and a lack of trust from stakeholders.
- Benefit: A Construction CPA ensures that your financial reports are compliant with industry regulations and accounting standards. They also provide detailed and accurate financial statements, giving you a clear picture of your business’s financial status and helping you make informed decisions.
Optimized Tax Planning and Strategy
Tax planning is a critical component of financial management for any business, but the construction industry faces unique tax challenges, such as deductions related to equipment, labor, and materials, as well as specific tax credits.
- Why It Matters: Without proper tax planning, your construction business could end up paying more taxes than necessary or missing out on valuable tax credits and deductions. Additionally, navigating complex tax regulations without expert guidance can lead to errors and potential audits.
- Benefit: A Construction CPA can develop a customized tax strategy that takes full advantage of available deductions and credits, while also ensuring compliance with tax laws. This can result in significant tax savings and reduce your overall tax liability.
Cash Flow Management
Cash flow is the lifeblood of any construction business. Managing cash flow effectively is crucial, especially in an industry where payment delays, fluctuating costs, and large capital expenditures are common.
- Why It Matters: Poor cash flow management can lead to financial strain, difficulty in meeting payroll, and an inability to invest in new projects or equipment. In extreme cases, it can even lead to business failure.
- Benefit: A Construction CPA can help you monitor and manage cash flow by forecasting income and expenses, identifying potential cash shortfalls, and advising on strategies to improve cash flow. This ensures that your business has the liquidity needed to operate smoothly and grow.
Risk Management and Mitigation
The construction industry is inherently risky, with potential financial, operational, and legal challenges. Effective risk management is essential to protect your business from unforeseen events that could impact its financial stability.
- Why It Matters: Without a solid risk management plan, your business may be vulnerable to cost overruns, project delays, contract disputes, or even financial insolvency.
- Benefit: A Construction CPA can assist in identifying and assessing risks, such as fluctuating material costs or project delays, and developing strategies to mitigate them. This proactive approach helps safeguard your business’s financial health and ensures long-term stability.
Assistance with Bonding and Financing
Securing bonding and financing is often necessary for taking on large construction projects. Lenders and bonding companies require detailed financial information and assurances of your business’s financial stability.
- Why It Matters: Inadequate financial documentation or poor financial performance can lead to difficulty in securing bonds or loans, limiting your ability to grow and take on new projects.
- Benefit: A Construction CPA can prepare the detailed financial statements and reports required by bonding companies and lenders. They can also provide financial analysis and advice to improve your business’s financial standing, increasing your chances of securing the necessary bonding and financing.
Strategic Business Planning and Growth
Beyond day-to-day financial management, a Construction CPA can play a key role in strategic business planning, helping you set long-term goals and develop plans to achieve them.
- Why It Matters: Without a clear strategic plan, your business may struggle to achieve sustained growth, expand into new markets, or adapt to changing industry conditions.
- Benefit: A Construction CPA can provide valuable insights and advice on business planning, including growth strategies, market analysis, and financial projections. Their expertise can help you develop a roadmap for success and ensure that your business is well-positioned for future growth.
Time Savings and Focus on Core Operations
Managing the financial aspects of a construction business is time-consuming and complex. By handling your accounting and financial planning needs, a Construction CPA frees up your time to focus on what you do best,running your business.
- Why It Matters: Time spent on financial management is time taken away from core business activities such as project management, client relations, and business development.
- Benefit: With a Construction CPA managing your financial affairs, you can dedicate more time and energy to growing your business, improving operations, and delivering high-quality projects. This can lead to increased productivity and profitability.
Peace of Mind
Perhaps one of the most valuable benefits of hiring a Construction CPA is the peace of mind that comes from knowing your financial matters are in expert hands.
- Why It Matters: The complexities of construction accounting and the ever-changing landscape of tax laws and regulations can be stressful for business owners. Mistakes or oversights can have serious consequences.
- Benefit: A Construction CPA provides reassurance that your financial management is accurate, compliant, and optimized. This peace of mind allows you to focus on other aspects of your business with confidence, knowing that your finances are in good order.
Contact Cooper Norman
Hiring a Construction CPA offers numerous benefits that can significantly enhance the financial health and operational efficiency of your construction business. From industry-specific expertise and accurate job costing to optimized tax planning and strategic business advice, a Construction CPA is an invaluable asset that can help your business thrive in a competitive industry. By partnering with a skilled CPA who understands the unique challenges and opportunities in construction, you can ensure that your business is not only compliant but also positioned for long-term success and growth. Contact us today with any questions!
How To Avoid Profit Fade in Construction
How to Avoid Profit Fade
“Don’t settle for second best!” Just about everyone has encountered this phrase in various commercials and ad campaigns over the years, and it’s a good ideal to aspire to.
Unfortunately, many construction businesses end up settling for second best, or worse, when it comes to the profitability of their projects. A common culprit is profit fade, when the forecasted margin on a job gradually decreases as work progresses because of unforeseen or unexpectedly high costs.
Causes of Profit Fade:
- Inaccurate Estimations:
- Underestimating project costs during the bidding process.
- Overestimating productivity or cost savings.
- Additional work added to the project that was not part of the original scope, often without proper cost adjustments.
- Inefficient resource allocation or delays in material procurement.
- Lack of regular progress tracking and adjustments.
- Site conditions or weather impacting productivity and timelines.
- Regulatory changes or permit issues causing delays.
- Subcontractors underperforming or requiring additional supervision.
- Subcontractor pricing disputes.
Profit fade is a persistent threat, but there are ways to fight back. Here is how you can avoid profit face in construction or other project based businesses.
Explore estimating improvements
Many, if not most, project losses can be traced back to suboptimal estimates, which in turn lead to inefficient bids. Review a set of your most recent estimates. Are they adequately detailed? Do they account for all the costs that ended up being associated with the job in question?
Also determine whether your estimators have enough training, patience and experience to perform at their best despite the recent fluctuations in inflation. Are they rushing through their work? Are they being unrealistic about the current price points for labor, materials and equipment usage?
Code everything
If you haven’t already, explore the benefits of assigning cost codes to every task typically associated with your jobs. Think of them as tiny price tags attached to each activity that allow you to see how much that task costs.
Establishing a sound cost code structure and using it consistently companywide, from estimators to project managers to accounting staff, is key to getting useful data. Over time, and with a solid sample size of jobs, you’ll be able to determine which activities cost the most and which ones cost too much.
Refine contractual terms
Well-defined contract terms and conditions are another way to minimize the potential for profit fade. Contract language should clearly define the nature and scope of the work to be performed. If possible, include a clause that limits how much, if anything, an owner can change while work is in progress before paying additional compensation under a formal change order process. From there, lay out straightforward steps for submissions and approvals of change orders so you can bill for additional work as soon as possible.
Additionally, explore the feasibility of including a price acceleration clause that allows you to adjust the contract price if materials or labor costs rise above a stated level. To add another layer of protection, ask for a deposit to buy and store materials before work begins.
Manage materials carefully
Indeed, the high cost of materials is arguably one of the chief culprits of profit fade these days. When bidding on a project, create a contingency plan for two or more alternative suppliers. Preferably, at least one of them should be local so you can get deliveries relatively quickly.
If possible, build up inventory levels with critical materials and long-lead items to insulate your company against supply chain slowdowns. Bear in mind that this will entail a substantial upfront investment and require you to be able to safely store the items.
Focus on situational awareness
Preventing profit fade comes down to situational awareness. By continuously monitoring key metrics associated with every project, you and your project managers can put yourselves in a better position to act prudently and decisively when costs start to rise. Contact our firm for help looking for ways to improve your construction company’s estimating and cost-tracking processes.
Construction Bookkeeping
Hiring a bookkeeper that has experience in the construction industry will help you not only when it comes time for taxes but will help you to keep all your finances in order throughout the entire year. Specializing in the unique financial needs of the industry, a construction bookkeeper ensures accurate job costing, tracks project expenses, and monitors cash flow to help you maintain healthy margins. They handle complex aspects like progress billing, change orders, and subcontractor payments, ensuring compliance with tax regulations and contract requirements. By providing real-time financial insights, a construction bookkeeper allows you to make informed decisions, reduce profit fade, and focus more on growing your business rather than managing numbers.
Don’t Let Your Profit Fade
By being aware of these common issues that construction companies often face, you can help prevent it before it happens. Make sure to focus on these issues so that you can start and end your projects in success without running into these common problems that will cause you to lose profit. Don’t just survive, but thrive!
How construction businesses can better manage their money
For construction businesses, financial management is notoriously complex. Contractors have to deal with the ebbs and flows of their respective markets, project-based pricing and collections, rising operating costs, and various other factors, not the least of which is bad weather!
Yet effective financial management is essential for your company to thrive. Here are some ways to better manage your money.
Follow strong billing procedures
Healthy cash flow, one of the most important aspects of financial management, depends on your business’s ability to both meet contractual obligations and receive timely payments. To this end, establishing a standard billing schedule for every job will make managing accounts less complicated and help you keep track of monthly revenue.
When drafting contracts, clearly include payment amounts and when they’re due, as well as penalties for late payments. Equally important, clearly outline a process for change order approvals and invoicing that allows you to bill for additional work as soon as possible. Diligently follow the billing schedule as projects or project phases are completed.
To help ensure prompt payment, make sure invoices are well-designed, detailed and include any necessary proof-of-work documentation. If you don’t already, offer electronic payment options to make paying quicker and easier. Last, be sure to set up automated reminders to regularly follow up on unpaid invoices.
Excel at materials management
Effective financial management also depends largely on how cost-efficiently you procure, store and use construction materials. Implement strategies to optimize all three of these actions while minimizing waste.
Begin by taking a hard look at how you capture, organize and share materials-related data across your projects. Do you have a centralized system for doing so? Are you tracking losses and proactively addressing how to prevent theft, mistakes and mismanagement? With the right system in place and technology supporting it, you can minimize excessive and unnecessary spending on materials.
From there, be sure you’re addressing the timely delivery of materials. Supply chain slowdowns or disruptions aren’t in the news as much anymore, but they’re still a challenge for many contractors.
Some construction companies maintain inventories of critical and long-lead items to ensure they’ll have the necessary materials as jobs come up. But doing so entails paying for storage facilities and investing time and resources into inventory management. Another strategy is to diversify your supplier base and include alternative local suppliers who can deliver materials of similar type and quality.
Keep a close eye on labor
Nearly all businesses need to confront the tricky issue of “rightsizing” their workforces and paying employees competitively. Construction companies have the added challenge of doing all this in the midst of a seemingly never-ending skilled labor shortage.
One thing that can help is quantifying your labor needs as precisely as possible. Determine how many workers are needed to complete each typical job task or how many are needed to work on each phase of the types of projects you usually perform. Obviously, you’ll need historical data to make such determinations, so be sure you’re capturing this information.
Compensation, benefits and taxes are also major factors. Indeed, knowing your true labor costs, often referred to as labor burden rate, is a mission-critical financial-management activity for construction businesses.
Embrace technology
Using up-to-date and secure financial management software and mobile devices tailored to the construction industry can help streamline financial activities related to estimating, job costing, payroll and invoicing. The right combination of tech assets can help:
- Automate calculations and processes,
- Create more accurate estimates,
- Track a variety of costs and accurately allocate them to projects, and
- Generate the necessary documentation for your records, as well as for financial reporting.
As always, however, selecting the right tech tools for your construction business’s distinctive needs and comfort level is the hard part. Choose your purchases and upgrades carefully, always with the goal of improving the clarity of your finances and your control of them.
Lay the foundation
Managing cash flow, materials, labor and technology costs for your hardworking construction company may seem as difficult as laying a solid foundation on unstable soil. But with the right personnel, policies, procedures and computing tools in place, it can be done. We’d be happy to help you review your construction company’s approach to financial management and target areas for improvement.
6 Ways Construction Companies Can Strengthen Cybersecurity
Some contractors might assume hackers won’t bother with smaller construction businesses. Sadly, they’d be wrong.
Construction companies tend to have high turnover rates, which means they store lots of personal data on past and present employees. And they usually have access to technical plans and information about building management systems, which can now often be accessed (read: hacked) online.
Perhaps worst of all, many construction businesses have limited IT resources and defenses, so they’re especially vulnerable. Here are six ways to fortify your cybersecurity defenses:
1. Conduct regular cyber risk assessments. Evaluate your systems to determine what kinds of data your staff generates and processes. Also identify where it’s stored. From there, you can implement the latest and optimal protective steps. Because technology changes rapidly, as does the sophistication of cyberattacks, follow these procedures at least annually.
2. Educate employees. Ensure every staff member knows how to properly use technology, handle confidential information and report cyberthreats. Provide targeted training on dangers such as:
- Phishing (socially engineered attempts to fool users into divulging sensitive data),
- Malware (invasive damaging software usually hiding in links or email attachments), and
- Ransomware (a type of malware that captures files and encrypts them, or even locks a device, enabling hackers to demand a ransom for decryption or to unlock the asset).
Cybersecurity training should also occur as part of onboarding, whenever a new device is issued and at least annually as a refresher. At Cooper Norman our IT professionals can assist you with implementation of tests that will help to train your employees.
3. Use multifactor authentication. Every one of your construction company’s devices, systems and apps should, at the very least, be password-protected. However, the latest standard is to require multifactor authentication, that is, multiple credentials, such as a password plus a numerical code, to add another layer of security. If your construction company’s employees use personal devices at work, instruct them to use multifactor authentication as well.
4. Keep software updated. As updates and patches are released, be sure they’re immediately downloaded onto your construction business’s systems and devices. And, again, if your workers use personal phones or other devices on the job, train and remind them to check for and download updates as soon as they become available.
5. Erase hard drives before disposal. Laptops, mobile devices, tablets, and even some printers and copy machines hold sensitive data and should be fully wiped before disposal. The same goes for leased equipment before returning it.
6. Look into cybersecurity insurance. This coverage is designed to mitigate losses from a variety of incidents, including data breaches, business interruption and network damage. At a minimum, a policy should cover liability for data breaches involving sensitive customer information, such as credit card numbers and driver’s license numbers.
Like any type of insurance, cybersecurity coverage should be bought only after careful due diligence and within a sensible budget. We’d be happy to help you assess such a purchase or better identify the costs associated with strengthening your construction company’s cybersecurity.
Mike Goettsche Earns the Certified Construction Industry Financial Professional (CCIFP) Designation
 Idaho Falls, Idaho, November 2023
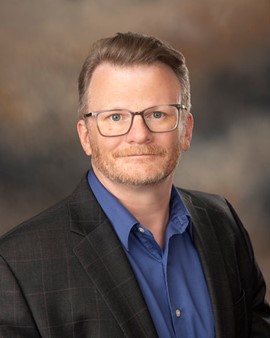
Cooper Norman is happy to announce that its senior consultant, Mike Goettsche, has achieved the certification of CCIFP (Certified Construction Industry Financial Professional).
Mike, a native of Idaho Falls, has been with Cooper Norman for 15 years. During that time, he developed a specialization in assisting companies in the construction industry. Achieving multiple degrees in accounting, economics, and industrial management as well as a Master of Business Administration, Mike brings knowledge and experience that give him “a better understanding of issues faced by construction companies beyond the financials and tax returns.” He is passionate about growing the construction industry as a niche for Cooper Norman by helping companies to achieve their goals.
The CCIFP designation is achieved through study and examination. Recertification is achieved by completing construction specific continuing education every three years. The accomplishment of this credential demonstrates a commitment to excellence and a dedication to continually improving. Only six individuals in Idaho currently hold this designation.
When Mike is not thinking about how to improve the industry, he is hiking, traveling around the world or finding a delicious new place to sample food. An avid sports fan, he is always interested in watching a good soccer game as well.
Please join us in congratulating Mike on this outstanding accomplishment!
Construction companies: Lean into tech to optimize accounting and financial management
The construction industry is renowned for its quality craftsmanship. However, it’s also sometimes known for a historical reluctance to adopt new technology.
When it comes to your construction company’s accounting and financial management, there’s never been a better time to lean into technology to improve how you handle these mission-critical functions. Here are some ideas to consider.
Review and automate processes
A good place to start is by identifying any remaining manual processes and, to the extent feasible, eliminate or automate these tasks. For example, are your employees keying in labor hours or using spreadsheets to certify payroll or manage accounting data? Do you have staff spending valuable time physically matching packing slips to invoices or filing hard copy documents in cabinets?
If any of those scenarios apply, explore electronic document management systems and tools that facilitate electronic data transfer rather than manual data entry. Automation enables faster, easier and more consistent processing. Using accounting software tailored to the construction industry, with features such as job costing, project management and contractor-specific reports, can help streamline payroll, invoicing and expense tracking to improve accuracy and save time.
Even if you have a reliable legacy system that works efficiently, there may be third-party tools available that can integrate with your system to add new functionality, better efficiency and improved user experiences. Explore whether there are better cloud-based and mobile tools on the market that allow more reliable and robust remote access and collaboration, ensuring data is updated and accessible from anywhere. This is particularly beneficial when managing multiple projects across different locations.
Another option is to migrate to an enterprise software platform that integrates critical functions such as project management, inventory management, customer relationship management and sales with accounting and financial reporting. Having your entire construction company on one platform tends to enable more consistent data-sharing across departments and enhance operational efficiency.
Perform regular financial analyses and reporting
Of course, optimizing your accounting function and financial management doesn’t end with automation. It’s critical to regularly conduct financial analyses to track cash flow, budget adherence and project profitability. Generating the right regularly scheduled financial reports will provide insights for making informed business decisions and identifying areas of concern.
Your objective is to manage regular expenses and job costs through careful monitoring and financial reporting. As you do so, be sure to have established robust internal procedures to safeguard against fraud and errors. These might include segregating financial duties so that one person doesn’t control all financial transactions or processes, conducting routine audits, and promoting ethical business practices.
Invest in training, consider outsourcing
As important as the right technology and processes are, effective accounting and financial management comes down to people. Well-trained employees are generally more accurate, productive and require less supervision. Hold regular training sessions to help your staff master the latest best practices, internal process changes and tech tools. Doing so will also keep them updated on current laws, regulations and accounting standards.
For smaller construction businesses, or those that just need some help, outsourcing may be worth considering. A carefully selected provider can eliminate or lessen the time-consuming burdens of hiring, training and retaining employees to perform accounting and financial-management duties. Strategic outsourcing involves engaging one or more outside professionals for specific or highly specialized tasks. It can boost productivity by freeing your staff to focus on core business activities or help with surges in labor needs attributable to seasonal work or multiple projects. Naturally, you’ll need to be reasonably assured of an acceptable return on investment of any outsourcing arrangement before you sign on the dotted line.
Embrace the future
Construction companies need not languish in the realm of dusty paper ledgers or outdated spreadsheets. By gradually and mindfully embracing the benefits of today’s technology, as well as fine-tuning processes and supporting employees, there’s a good chance you can streamline your accounting function and improve financial management. Please contact our firm for help.
What contractors need to know about bonding capacity
Construction companies are required to obtain surety bonds on many types of projects, particularly those that are publicly funded. The bonds essentially guarantee that the work will be completed one way or another. Contractors are urged to manage their operations and financials carefully to preserve or, better yet, increase bonding capacity. But what is this, really?
The three Cs
Simply defined, bonding capacity is the maximum amount of credit a surety will extend to a contractor. It’s often expressed as the largest single project for which the surety would issue the subject company a bond. Capacity is, in fact, one of the “three Cs” of bonding:
1. Character. This refers to whether a construction company can be trusted to honor its contract obligations. A surety will look at your business’s reputation, including its track record of successfully completing projects and consistency paying suppliers. Transparency about financial information and complete answers on the bonding application are also good indicators of character. So are the quality and timeliness of your communication with the surety.
2. Capital. This indicates financial strength. Many sureties look at adjusted working capital, the difference between current assets (such as cash and accounts receivable) and current liabilities (such as accounts payable and short-term debt). A surety will scrutinize your financial statements to set your bonding limit, which generally ranges from 10 to 20 times your adjusted working capital.
3. Capacity. As mentioned, this is the maximum amount of bonding you can qualify for, based on your total ability to fulfill the contract in question. Sureties look at your equipment, labor and other resources, as well as the type and size of contracts recently completed.
For example, if you want to secure a $10 million contract, but the largest contract you’ve completed to date is $5 million, the surety will likely question your capacity to deliver a project of that size. With the cost of materials rising, an increasingly common problem for many contractors is getting bonded for projects of the same scope that now cost more to complete.
Ideas for boosting capacity
Here are a few ways you might be able to boost your bonding capacity:
Take out a shareholder loan. Also called a capital injection, these loans are among the quickest, easiest ways to “inject” cash into the business and increase working capital. A shareholder loan is typically subordinated to the surety to be treated as equity and working capital. Thus, you’ll need permission from the surety to repay it.
Step up collections. Sureties usually remove receivables that are more than 90 days old from working capital unless you can show they’ve been collected or will be soon. Focus on collecting receivables in or near this 90-days-old bracket.
Sureties also tend to remove from working capital amounts a construction business has loaned to related parties, such as an affiliated company or subsidiary. Ensure these amounts are paid back or reduced before year end.
Defer insurance renewals. Work with your insurance rep to push back any renewal payment dates that fall before year end. Doing so will reduce prepaid expenses for the year, which will increase working capital.
Strengthen your position
Now’s a good time to build up your bonding capacity as public infrastructure jobs continue to come online. We’d be happy to help you better understand and strengthen your construction company’s working capital position.
8 Ways Construction Accountants Help Construction Businesses Proactively Manage Their Supply Chains
Construction Accountants
The construction industry is no stranger to the challenges of supply chain disruptions, an issue exacerbated during the pandemic. While global supply chains are gradually stabilizing, materials shortages and delays continue to impact project timelines and budgets. For construction companies, proactive supply chain management is essential. Partnering with construction accountants can further enhance strategies to mitigate risks, improve financial planning, and ensure successful project delivery.
8 Ways Construction Accountants Help Construction Businesses
Here are eight key approaches, optimized by the insights of construction accountants:
1. Develop and Maintain Strong Supplier Relationships
Building solid relationships with suppliers is crucial, especially during uncertain times. Construction accountants can help evaluate payment histories, manage early payments, and track financial trends to nurture goodwill with suppliers. Maintaining open communication ensures you’re aware of potential supply chain issues early.
2. Be Transparent with Customers
Delays or material shortages can strain relationships with clients. By addressing potential supply chain concerns during the bidding and preconstruction phases, contractors can set clear expectations. Construction accountants can assist in creating transparent cost structures that accommodate these challenges.
3. Put an Expiration Date on Your Bids
Construction accountants can analyze historical data and market trends to recommend optimal bid expiration periods, such as 30 days. Keeping bids valid for shorter durations protects your bottom line from unexpected cost increases or material unavailability.
4. Negotiate Contractual Protections
Protecting your business with well-defined contract terms is a must. Construction accountants provide valuable insights into contract negotiations, ensuring provisions for delays tied to supply chain disruptions are fair and financially sound.
5. Order in Advance
Procuring materials and equipment in advance can mitigate sudden shortages and lock in current pricing. Construction accountants can evaluate cash flow and budgeting to determine whether bulk purchasing or off-site storage is feasible for your business. They can also assist in negotiating early-release funds for essential purchases.
6. Diversify Your Supplier Base
Relying on a single supplier is risky. Construction accountants can analyze your financial exposure and help identify ways to diversify your supplier network by region or supplier size, reducing the risk of disruptions caused by natural disasters, economic shifts, or geopolitical instability.
7. Develop Contingency Plans
Being prepared for unforeseen circumstances is critical. Work with construction accountants to forecast alternative scenarios, such as sourcing materials from other contractors or modifying project designs to accommodate readily available supplies.
8. Invest in Supply Chain Management Software
Modern supply chain management software can streamline operations, track shipments, and identify vulnerabilities. Construction accountants can evaluate the financial ROI of such tools, ensuring the investment aligns with your company’s objectives.
Stay Ahead of Pricing Volatility
One of the biggest challenges in managing supply chains is fluctuating material costs. Construction accountants can monitor market trends and provide financial modeling to account for potential price surges. By preparing accurate cost estimates and setting up contingency funds, your business can remain competitive while safeguarding project profitability.
The Role of Construction Accountants in Supply Chain Success
Construction accountants are more than number crunchers; they are strategic partners who can analyze financial data, assess risks, and create plans that keep your projects on track despite supply chain challenges. By leveraging their expertise, you can make informed decisions and strengthen your business’s resilience.
Optimize Your Supply Chain with Construction Accountants
Whether it’s managing costs, forecasting budgets, or enhancing operational efficiency, construction accountants play an integral role in navigating supply chain complexities. Contact us to learn more about how we can help your business overcome supply chain challenges and achieve long-term success.